Nov 21, 2026
Nov 21, 2026
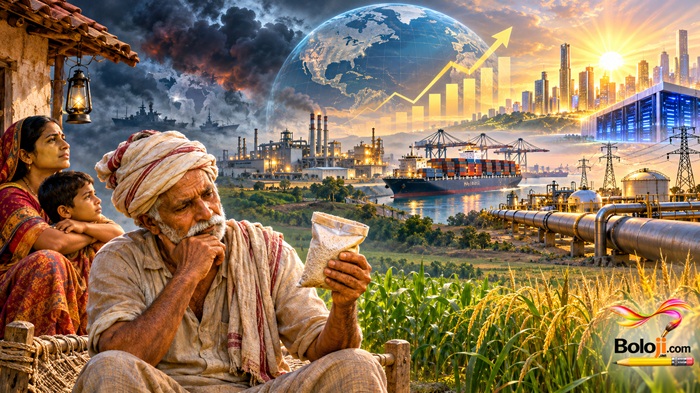
What does an Indian farmer buying fertilizer have in common with a European manufacturer buying gas? How does a negotiation in Shenzhen change the arithmetic of a factory that has yet to be built? If the world can find another supplier when war interrupts a shipment, who pays the difference? And what does a respectable global growth rate tell us about the countries that can scarcely afford to keep the lights on?
Two figures from the World Trade Organization capture the economy I see taking shape. In the first half of 2026, liquefied natural gas (LNG) exports from the Middle East fell by roughly 47%. Yet global LNG exports declined by only 1%, as other suppliers stepped in. From the perspective of the world economy, that was an extraordinary adjustment. From the perspective of an importer forced to compete for a replacement cargo at short notice, it could still be a punishing experience. Both judgments can be true.
By 2030, I expect the global economy to be larger, still deeply interconnected, and considerably more expensive to insure against political upheaval. I expect annual world growth to settle around 3% toward the end of the decade, provided the Gulf conflict does not produce a prolonged energy shortage and the technology investment boom avoids a sharp reversal. That is my judgment. The IMF’s nearer-term benchmark is 3.1% growth in 2026 and 3.4% in 2027. The consequential question is how much of that additional income will improve living standards and how much will merely pay to keep economies functioning through the next disruption.
What ‘Hormuz’ Can Do to a ‘Household Budget’
On November 18, Reuters reported that Washington had tightened its blockade of Iran by imposing curbs on oil transfers at sea. Yet oil prices settled lower that same day, as rising US inventories reinforced expectations of surplus supply. I find that juxtaposition more instructive than a prediction of permanently expensive oil. A war can endanger tomorrow’s delivery even when there is ample oil in storage today.
Consider an Indian fertilizer producer deciding whether to commit to a season’s output. A fall in the quoted price of oil offers limited comfort if the gas the plant needs could arrive late or at an unaffordable price. Somebody must carry that risk. The producer can pay for a more secure contract, the government can absorb a higher subsidy bill, or the farmer can face higher input costs. What begins as a confrontation in the Gulf can end as a budget decision in New Delhi or a planting decision in Telangana. The WTO has already documented how the conflict disrupted energy, fertilizer, and freight markets.
By 2030, I expect import-dependent countries to pay more attention to the timing of energy security. An additional supplier helps this winter. Storage buys weeks during an interruption. Domestic electricity generation can reduce some fuel imports over several years. Each solves a different problem. A government that announces an ambitious renewable-energy target but neglects storage, transmission, and immediate supply contracts leaves its citizens exposed during the years it takes to deliver that ambition.
A ‘Two-Month Truce’ and a ‘Twenty-Year Factory’
On November 9, China effectively extended its trade truce with the United States by two months, ahead of the Asia-Pacific Economic Cooperation (APEC) summit in Shenzhen. Put yourself in the position of a manufacturer considering a plant intended to operate for twenty years. Two months of tariff certainty may be enough to dispatch a shipment. Would you borrow money on the strength of it to build a factory?
I expect this mismatch between political and investment calendars to reshape trade more decisively than declarations about the end of globalization. A company may retain its Chinese supplier, qualify another in India or Southeast Asia, and hold more inventory near its American customers. Its purchases may cross as many borders as before. Its costs will nevertheless rise because it must audit two suppliers, finance additional stock, and divide orders that once earned a volume discount.
There is an opportunity here for countries able to offer dependable customs clearance, electricity, and commercial rules. There is also a warning for governments offering lavish factory subsidies. A multinational may accept a subsidy to establish a second production site while keeping its engineering expertise and most valuable orders elsewhere. I would judge an industrial policy by what domestic suppliers learn to make after the foreign investor arrives.
The AI Boom Has a Geography
The WTO estimates that goods enabling AI, including semiconductors and servers, accounted for 47% of global merchandise trade growth in the first half of 2026. That figure concerns the increase in trade. Its significance is the degree to which one investment cycle now influences the global outlook. A slowdown in data-center construction could reach component manufacturers and their workers well before an ordinary consumer notices any change in the AI tools on a phone.
My more optimistic scenario for 2030 depends on what happens after the servers are installed. A hospital that uses its existing scanners to examine more patients, a manufacturer that catches defects before an entire batch is spoiled, or a small exporter that can afford to serve customers in several languages creates a gain beyond the technology industry. If such gains spread, productivity can offset some of the cost of geopolitical fragmentation. If adoption stalls outside a handful of wealthy firms, the world will have built expensive infrastructure whose financial returns depend on a narrow circle of buyers.
For India, the distinction is significant. The Reserve Bank of India’s October bulletin records growth projections of 7% for both fiscal 2026–27 and 2027–28. I see a genuine opening in that momentum, alongside a vulnerability in the services model. If AI allows five people to complete work that once required ten, an Indian firm billing by the hour faces pressure even as its technical capability improves. A firm paid to deliver a measurable business outcome has a better chance of retaining part of the productivity gain. By 2030, the terms on which India sells its expertise could matter nearly as much as the number of engineers it trains.
The Bill That ‘Outlives’ the War
Even a diplomatic breakthrough would leave Europe with an economic obligation extending well beyond this decade. Ukraine, the World Bank, the European Commission, and the United Nations estimated that damage sustained through December 2025 had already generated almost $588 billion in recovery and reconstruction needs over ten years. That was nearly three times Ukraine’s estimated 2025 GDP. A peace agreement could improve the conditions for investment immediately. It could scarcely restore a power station or return a displaced family to a habitable home on the day of signature.
I worry most about countries confronting several bills at once. The IMF projects public debt in emerging market and developing economies to climb from 74% of GDP in 2025 to 84% in 2031. Those averages conceal vast differences in borrowing costs. A wealthy government can finance an energy reserve on tolerable terms. A heavily indebted fuel importer may have to postpone a transmission line to pay for this year’s fuel, perpetuating the very dependence it needs to escape. That is how a temporary geopolitical shock can become a lasting development gap.
Final Thoughts
I would revise my 2030 outlook upward if Gulf shipping becomes reliably insurable again, US–China trade arrangements last long enough to support capital investment, and AI begins to lift output across ordinary businesses. I would revise it downward if prolonged energy disruption coincides with a retreat in technology spending. The first would squeeze household purchasing power just as the second weakened the investment sustaining global demand.
When I judge the economy at the decade’s end, I will begin with four questions. Could the farmer afford fertilizer when the planting window opened? Could the manufacturer commit to a factory without betting its future on the next summit? Did the productivity gains from AI reach workers, customers, and smaller firms? And when the world congratulates itself on another year of growth, how many people will be able to say that their own lives grew more secure?
21-Nov-2026
More by : P. Mohan Chandran